HYPOTHETICAL EXAMPLE
An operational scenario
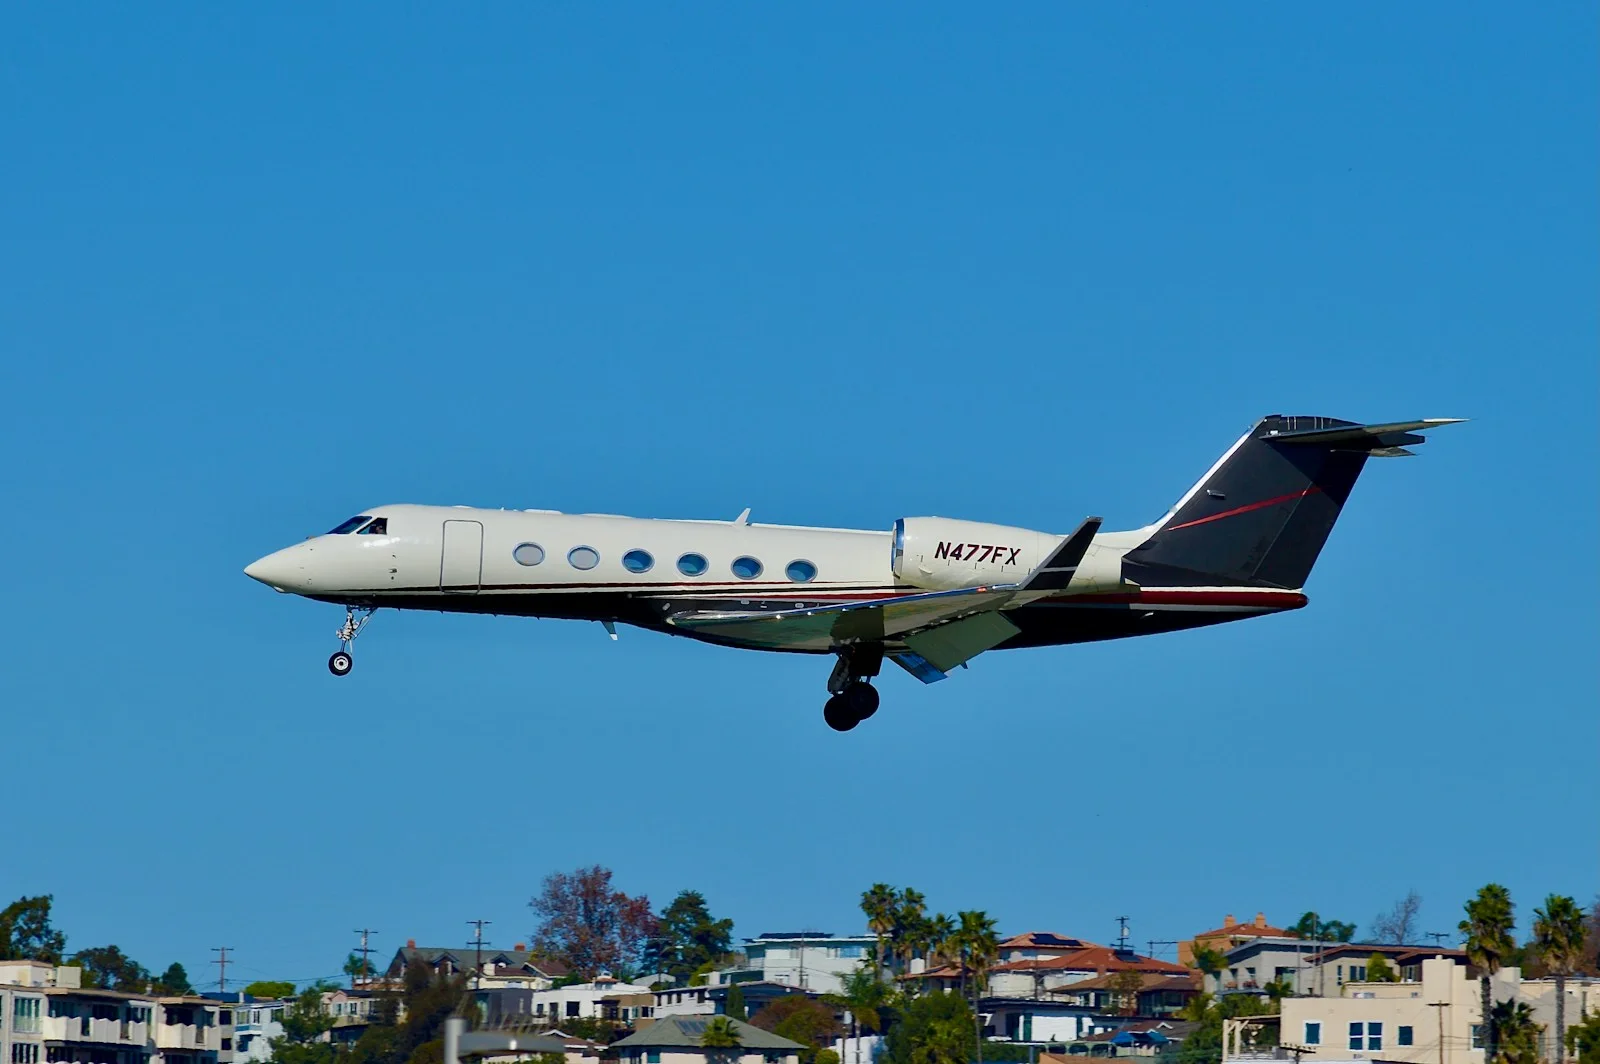
A business jet suffers substantial damage while parked during a storm. Repair cost, insured value, deductibles, salvage rights and any settlement conditions become separate parts of the analysis.
Illustrative example only; this is not a Montridge client or reported claim.
The insurance distinction
An agreed or stated value discussion must be tied to the actual form. Aircraft liability concerns third-party claims; it does not replace hull insurance. Coverage while parked, taxiing or flying depends on the selected terms and restrictions.
What to examine
Reconcile insured values with the aircraft’s configuration, equipment, financing and market evidence. Review partial versus total loss treatment, repair arrangements, geographic limits and any required notifications following modifications.
Evidence to gather
- Aircraft schedule and valuation evidence
- Equipment and modification list
- Finance or lease requirements
- Hull form, deductibles and endorsements
Questions for your review
- What valuation basis is actually in the policy?
- How are installed upgrades treated?
- Which deductibles apply to the circumstances of loss?
References and review status
- USAIG aircraft coverage FAQ
Example of insurer-specific hull liability and passenger distinctions; its specific terms must not be generalized - AOPA discussion of aircraft underinsurance
Valuation review context; no specific settlement promise - USAIG buying aviation insurance
General aircraft coverage context; actual form required
References support the indicated background topic. Review questions are educational analysis; no specific policy specimen has been supplied. Source checks: November 12, 2026.